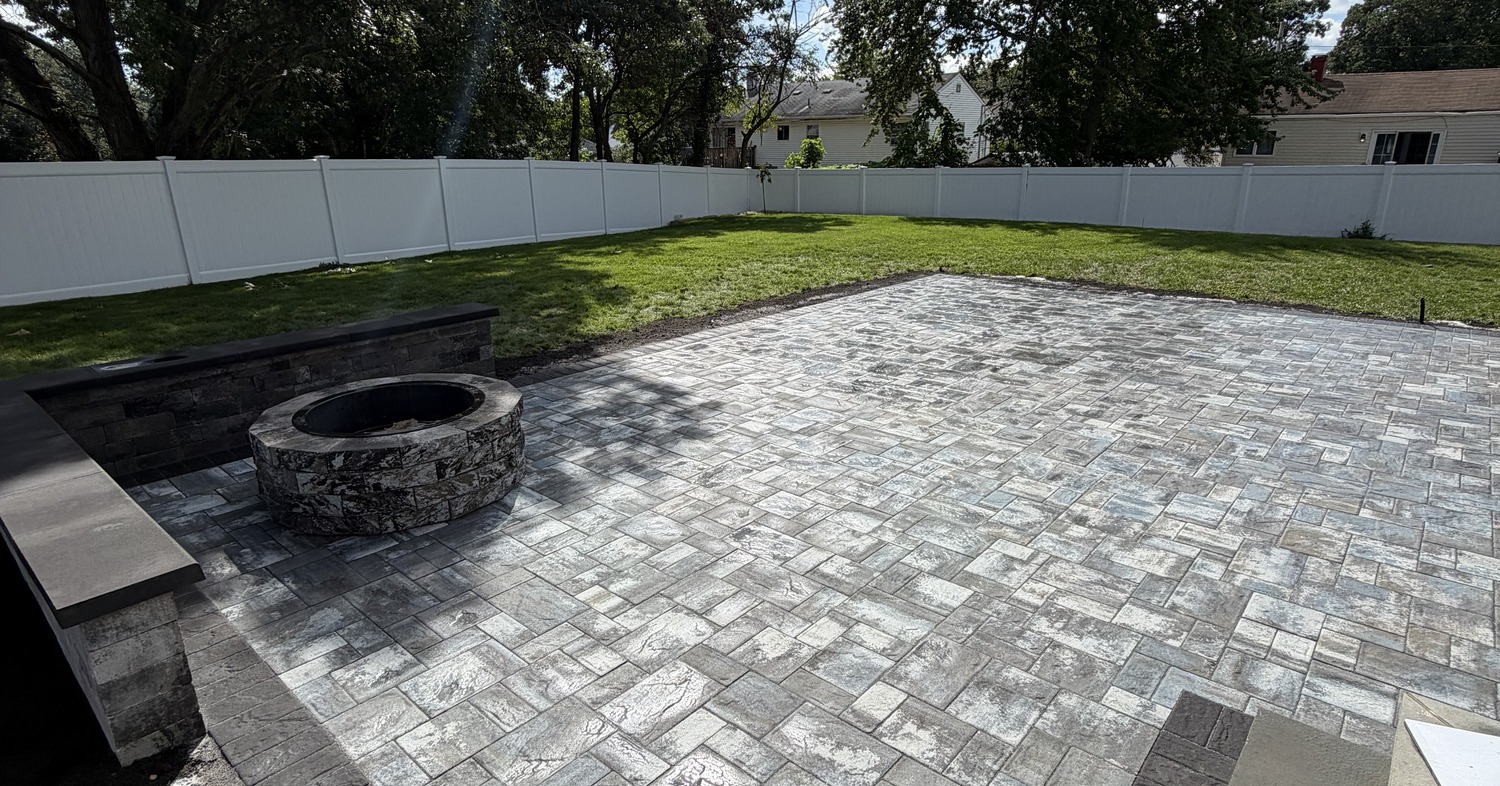
Patio financing on Long Island makes a professional paver patio possible without paying the full amount upfront. A 400 square foot patio with a fire pit and sitting wall can run $12,000 to $20,000 installed, and most Nassau County homeowners prefer to spread that over monthly payments rather than drain savings.
We have helped more than 2,000 families build patios across Long Island over the past 15 years, and many of them used financing to get started sooner. This guide covers the payment plan options available in Nassau County, what the monthly numbers actually look like, and how to choose the right path for your project.
Quick answer: Patio financing on Long Island is available through contractor-partnered lenders like Lyon Financial, home equity lines of credit, personal loans, and credit cards. Monthly payments on a $15,000 patio can range widely depending on the term and interest rate you qualify for. Affordable Patio offers financing through Lyon Financial, which advertises terms up to 30 years and loans up to $200,000. Confirm current rates and terms directly with the lender, since they can change and depend on your credit profile.
Table of Contents
Financing Options for Nassau County Homeowners
Home improvement financing in Nassau County falls into four main categories, and each one fits a different situation. The right choice depends on how much equity you have, how fast you need the money, and how long you want to pay it off.
Contractor-partnered lenders like Lyon Financial specialize in outdoor living projects and offer terms designed for patios, pools, and outdoor kitchens. Home equity lines of credit use the equity in your house and carry lower rates but take longer to set up. Personal loans from banks and online lenders fund quickly and need no collateral. Credit cards work for smaller projects or deposits when a promotional zero-percent rate is available.
Patio financing on Long Island is more accessible than most homeowners realize. Approval often takes 24 to 48 hours, and funds can be available before the project starts. The key is matching the loan term to the project size so the monthly payment fits comfortably in your budget.
Home improvement financing Nassau County residents use most often falls into the personal loan or contractor-lender category. Both offer fixed monthly payments with no lien on your property. The application is simple, the approval is fast, and the funds arrive before the first shovel hits the ground.
Lyon Financial Patio Loans
Lyon Financial is the lender we partner with at Affordable Patio. They specialize in outdoor living projects and understand the value that a paver patio adds to a Nassau County home. Their application process is straightforward, and most homeowners get an answer within one business day.
Lyon Financial advertises low fixed rates, terms up to 30 years, and loans up to $200,000, with no equity or appraisal required. There are no prepayment penalties, which means you can pay the loan off early without extra fees. A fixed rate means your monthly payment stays the same for the life of the loan, though the exact rate and term you qualify for depend on your credit profile and should be confirmed directly with the lender.
The application walks through applicant information, loan request and contractor details, identification verification, residency and project details, employment details, and final agreements. Lyon Financial’s program does not require home equity or an appraisal to apply, which is an advantage for homeowners who do not want to put their property up as collateral through a traditional home equity loan. Specific approval timelines and credit requirements vary and are best confirmed directly with Lyon Financial.
We can start the Lyon Financial application at the same time as your free estimate. By the time we finalize your patio design, financing is typically approved and ready. That means no delay between saying yes to the design and breaking ground. Learn more about Lyon Financial’s outdoor living loan programs on their website.
Home Equity Lines of Credit for Patio Projects
A home equity line of credit, known as a HELOC, uses the equity in your Nassau County home as collateral. Because the loan is secured, interest rates are typically lower than personal loans or credit cards, though actual rates vary by lender, loan amount, and your credit profile. Check current rates with your bank or credit union before deciding, since HELOC pricing changes with broader interest rate conditions.
The advantage of a HELOC for home improvement financing in Nassau County is generally a lower monthly payment compared to an unsecured loan of the same amount, because the rate is usually lower. Interest on a HELOC may be tax-deductible when the funds are used to improve the home that secures the loan, but this depends on your individual tax situation. We are not tax advisors, so confirm deductibility with your accountant or tax professional before relying on it.
The downside is speed. A HELOC can take several weeks to close, which means you need to plan ahead. There are also closing costs that vary by lender, which eat into the savings from the lower rate. For a smaller patio project, closing costs on a HELOC can sometimes make it more expensive overall than a personal loan with a slightly higher rate, so it is worth comparing the total cost of both options.
A HELOC works best for large projects over $20,000 where the low rate saves more than the closing costs add. Combining a patio with an outdoor kitchen, a pool deck, or a driveway is where the HELOC math starts to make sense.
Personal Loans for Patios
A personal loan from a bank, credit union, or online lender is the fastest way to fund a patio project. Most personal loans close within a week, and some online lenders fund in one to two business days. No home equity is needed, and the loan is unsecured.
Rates on personal loans for home improvement financing in Nassau County vary widely depending on your credit score, income, and the lender. Generally, borrowers with stronger credit profiles qualify for lower rates. Terms commonly run from 2 to 7 years, which means higher monthly payments than a longer-term HELOC but no closing costs.
Paver patio payment plans through a personal loan are straightforward. You borrow a fixed amount, make fixed payments, and the loan ends on a set date. There is no draw period, no variable rate, and no risk of the lender reducing your credit line. The example table below shows what payments look like at a sample rate so you can see how term length affects the monthly cost.
Credit unions often offer competitive personal loan rates. If you belong to one, check their home improvement loan products before applying elsewhere, since rates and origination fees can differ meaningfully between a credit union and an online lender.
Credit Cards and Promotional Rates
Credit cards work for patio financing on Long Island when the project is small or when you can pay the balance before a promotional rate expires. A zero-percent introductory APR card can give you a year or more to pay without interest, which turns a smaller deposit or a small walkway project into an interest-free payment plan. Check the specific card’s offer for the exact promotional period and the standard rate that applies afterward.
The risk is clear. If the balance is not paid in full before the promotional period ends, the card’s standard interest rate applies, which is often significantly higher than a personal loan or HELOC rate. That turns a manageable payment into an expensive one fast. Credit cards are not the right choice for a full patio project over $10,000 unless you have a concrete plan to pay it off within the promotional window.
Some homeowners use a credit card for the deposit and a personal loan or Lyon Financial for the balance. That combination captures the zero-percent rate on a portion of the cost while locking in a fixed rate on the rest. It takes discipline to manage two payments, but the interest savings can be worth it.
What Monthly Payments Actually Look Like
The monthly cost of patio financing on Long Island depends on three numbers: the loan amount, the interest rate, and the term. Here is what those payments look like for common patio project sizes in Nassau County.
| Patio cost | 5-year at 9% | 7-year at 9% | 10-year at 9% | 15-year at 9% |
|---|---|---|---|---|
| $8,000 | $166 | $131 | $101 | $81 |
| $12,000 | $249 | $197 | $152 | $122 |
| $15,000 | $311 | $246 | $190 | $152 |
| $20,000 | $415 | $328 | $253 | $203 |
These numbers assume a 9 percent fixed rate as an illustrative example only, not a quoted or guaranteed rate. Your actual rate depends on your credit profile, the lender, and market conditions at the time you apply, and could be lower or higher than this example. Every estimate we provide at Affordable Patio includes the option to apply for financing at the same appointment so you can see real numbers for your situation.
Paver patio payment plans at the 15-year term keep the monthly number low, but you pay more in total interest. A 5-year plan costs more each month but saves thousands over the life of the loan. Most of our Nassau County customers choose 7 to 10 year terms as the sweet spot between affordable payments and reasonable total cost. Patio financing on Long Island works best when the term matches how long you plan to stay in the home.
How to Qualify for Patio Financing
Most lenders that offer home improvement financing in Nassau County look at three things: your credit score, your income, and your debt-to-income ratio. Here is what each one means for your approval.
Credit score requirements vary by lender and by loan type, and generally secured loans like HELOCs carry stricter requirements than unsecured personal loans or contractor financing. Rather than rely on specific score thresholds that change over time, check directly with each lender for their current minimum requirements before applying.
Income verification is straightforward. Most lenders accept pay stubs, tax returns, or bank statements showing consistent deposits. Self-employed borrowers may need two years of tax returns. The goal is to show that you earn enough to cover the new monthly payment on top of your existing obligations.
Debt-to-income ratio measures how much of your monthly income goes to debt payments relative to your gross income. Lenders generally prefer a lower ratio including the new patio loan payment, though the exact threshold they will approve varies by lender and by the rest of your financial profile.
If your credit does not meet a lender’s standard requirements, you may still qualify through a co-signer or by putting down a larger deposit. Some contractors offer in-house payment plans for smaller projects. We always recommend checking your credit report at AnnualCreditReport.com before applying so there are no surprises.
Does a Patio Pay for Itself at Resale
Outdoor living improvements like paver patios are often cited by real estate professionals as features that appeal to buyers, and a well-built patio can recoup a meaningful portion of its installation cost at resale. The actual return varies widely based on your local market, the specific property, and buyer preferences at the time of sale, so we cannot promise a specific resale figure. We are not real estate professionals, and homeowners should talk to a local agent for guidance specific to their property and market.
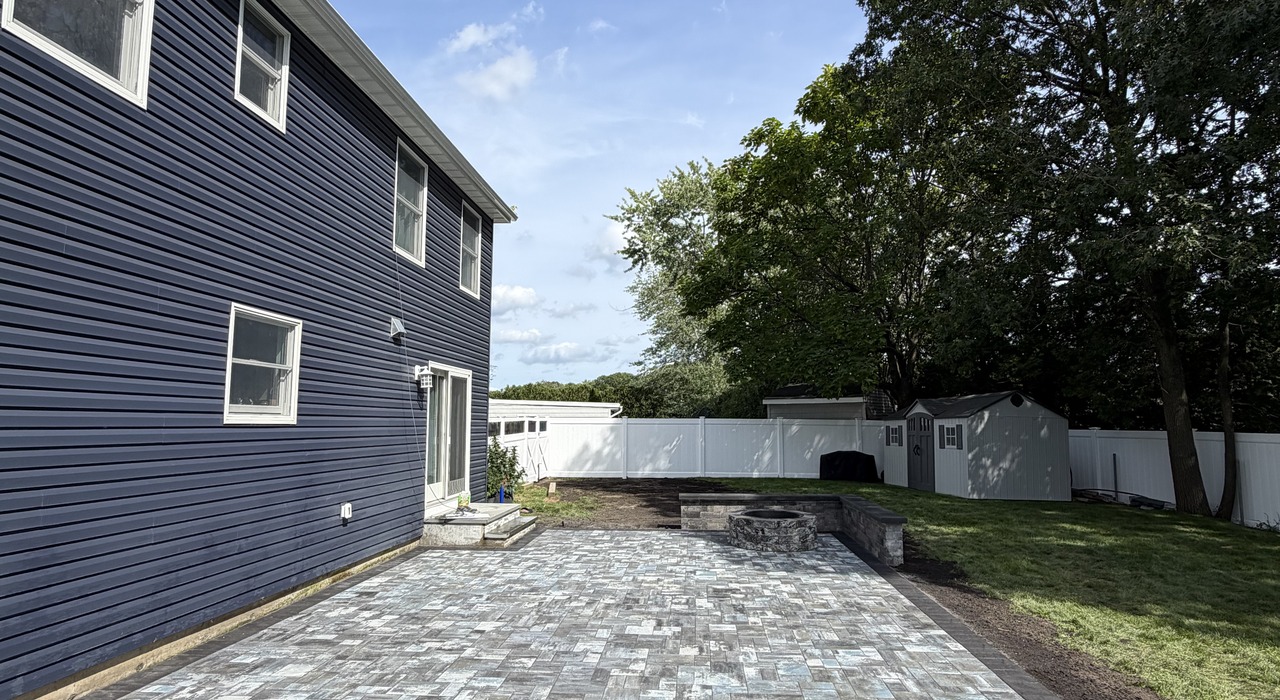
What we can speak to is installation quality. The return depends heavily on the quality of the installation, the materials used, and how well the patio integrates with the house and yard. A Cambridge Pavingstone patio with a fire pit and sitting wall in a well-landscaped yard tends to hold its value better than a patio that was installed poorly. A poorly installed patio with weeds and shifting pavers is far less likely to add value.
Patio financing on Long Island can make sense even when you factor in the cost of interest, since financing lets you build the quality patio you want now rather than waiting years to save the full amount in cash. The example payment table above shows how the monthly cost compares across different terms, which can help you weigh the financing cost against the years of use and any value the improvement may add.
The key is building quality from the start. We use Cambridge Pavingstones with ArmorTec, full excavation with a compacted gravel base, and proper drainage on every job. That is the kind of installation that holds its value. Cutting corners to save $2,000 upfront often costs more than $2,000 at resale when buyers notice the results.
Patio financing on Long Island gives you a way to invest in quality without compromise. Instead of choosing a smaller patio or cheaper materials to fit a cash budget, you can build the patio you actually want and pay for it over time. The resale math works in your favor as long as the installation is done right.
Frequently Asked Questions
Can I finance a patio with less than excellent credit?
Possibly. Approval and the rate you are offered depend on the lender’s specific requirements and your full financial profile, not just your credit score. A co-signer with stronger credit can sometimes help you qualify for better terms. If a specific lender does not approve you, a secured personal loan or a contractor deposit plan may be worth exploring. Check with the lender directly for their current approval criteria.
How long does it take to get approved for patio financing?
Approval timelines vary by lender and loan type. Online personal loan lenders and contractor-partnered programs like Lyon Financial tend to respond faster than secured loans. HELOCs generally take longer because they involve an appraisal and closing process. Confirm current processing times with the specific lender you are applying through.
Is there a minimum project size for financing?
Minimum loan amounts vary by lender. For smaller projects, a zero-percent credit card or a contractor deposit plan is usually the simplest path. Paver patio payment plans tend to make the most financial sense for larger projects where the monthly payment savings are meaningful relative to any fees or interest.
Does financing delay the project start date?
Typically no. We process the financing application at the same time as the estimate and design phase, so by the time your patio layout is finalized, financing is often already approved. We coordinate the timeline so that construction can begin once you approve the design and the funding is in place.
Are there prepayment penalties?
Lyon Financial advertises no prepayment penalties. Prepayment terms vary by lender for personal loans and HELOCs, and some HELOCs carry early closure fees within the first few years. Always confirm prepayment terms before signing, because an early payoff can save money in interest if there is no penalty.
Can I combine financing with a seasonal discount?
Yes. Home improvement financing in Nassau County can be combined with any seasonal promotions or package discounts we offer. Financing the discounted amount means lower monthly payments and less total interest. Fall and early spring are typically when the best pricing is available because scheduling is more flexible.
Next Steps
Patio financing on Long Island removes the biggest barrier between wanting a patio and having one. Whether you choose Lyon Financial, a HELOC, or a personal loan, the monthly cost of a professional paver patio is less than most homeowners expect.
We are a Preferred and Certified Cambridge installer with more than 15 years of experience across Nassau County and Suffolk County. Every patio comes with a 3-year workmanship warranty and a free estimate that includes financing options. See the example payment table above for a sense of what monthly payments can look like at different project sizes and terms.
Ready to see your options? Call (631) 275-3142 for a free estimate, or reach us through our contact page. We will bring financing paperwork to the appointment so you can see real numbers before you commit. Visit our Nassau County service page to see our recent work across the area, or use our Build and Price tool to get a quick estimate online.